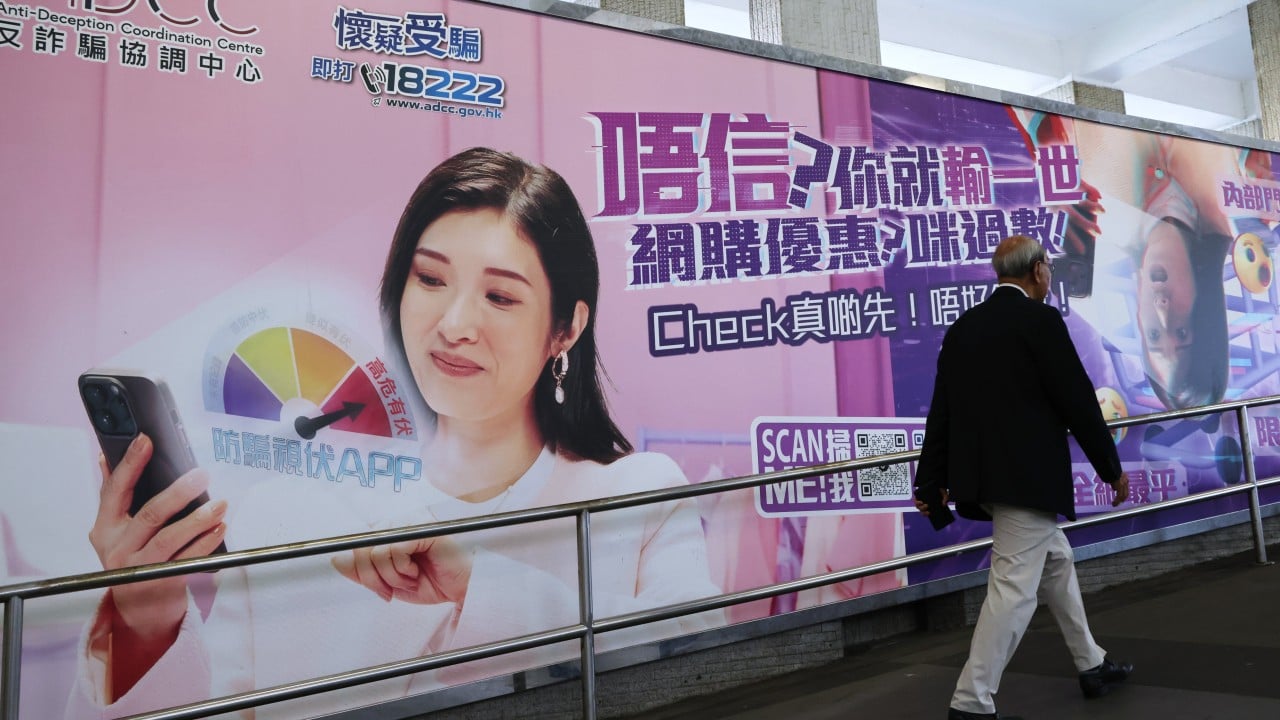
Another headline runs across the news feeds. An eighty-year-old woman in Hong Kong drops six million dollars into the digital void, handing her life savings to a smooth-talking avatar on a screen. The public gasps. The media rolls out its standard, tired narrative about elderly digital illiteracy, gullible grandparents, and the predatory wolves prowling the dark corners of the internet.
Everyone nods along with the lazy consensus. We point our collective fingers at lack of tech education, install a few patronizing cybersecurity pamphlets on our parents' phones, and pat ourselves on the back for diagnosing a societal rot. In similar updates, read about: The Escalation Calculus Behind Washington and Tehran.
We are missing the entire point.
The story is not about an old woman failing to spot a deepfake or clicking the wrong link. It is about a trillion-dollar financial architecture that has completely automated trust while stripping away human friction. When wealth management becomes a zero-touch, frictionless API call wrapped in high-definition UI, deception ceases to look like a sketchy back-alley mugging. It looks like a high-yield savings account backed by a simulated Bloomberg terminal. USA Today has provided coverage on this important topic in great detail.
I have spent years inside the compliance and fraud engineering rooms of major financial institutions. I have watched engineering teams obsess over conversion funnel velocity while compliance departments treat verification as a box-ticking exercise designed to pass regulatory audits rather than stop actual harm. The system is rigged. Not by malicious cartoon villains, but by hyper-optimized conversion loops that treat human gullibility as a monetizable asset class.
The Myth of the Digital Native Defense
Every time a multi-million-dollar scam hits the wire, the tech-savvy crowd smugly mutters that it could never happen to them. They tweet about two-factor authentication and hardware keys from their iPhones while ignoring the fundamental flaw of modern digital interfaces.
We assume that fraud victims are stupid. That is an ego defense mechanism. It protects us from confronting a terrifying reality: the modern internet has evolved past human cognitive defenses.
When a fraudster targets an eighty-year-old with six million dollars to move, they are not relying on a poorly spelled phishing email from a Nigerian prince. They are deploying institutional-grade social engineering, complete with multi-month relationship building, real-time market data integration, and institutional branding that mimics regulated brokerages down to the exact hex code of their color palettes.
Imagine a scenario where a twenty-five-year-old software engineer falls for a synthetic identity crypto scheme because the Telegram channel has fifty thousand active members, verified admin badges, and daily trading returns that outpace the S&P 500. It happens every single day. The age gap is a distraction. The vulnerability is structural, not generational.
We have built an economy where verification is outsourced to visual cues that can be generated by a teenager with an open-source GitHub repository in ten minutes.
The Frictionless Trap
For decades, banking had a built-in defense mechanism called friction.
If you wanted to wire six million dollars in 1995, you had to walk into a physical branch. You had to sit across from a loan officer who knew your name, your family, and your risk tolerance. You had to sign paper forms. That process took hours, sometimes days. It gave the human brain time to panic, to second-guess, to talk to a cynical relative over Sunday dinner.
Modern fintech destroyed friction in the name of user experience. We wanted instant settlements, one-click investments, and API-driven wealth transfers. We got them. And so did the criminal syndicates.
When you remove friction, you remove the pause button of human cognition. A fraudster does not need to convince you for three weeks in person anymore; they just need you to tap authorize on a push notification while you are half-asleep on your living room couch.
The financial services industry loves to talk about risk management, but their definition of risk is almost exclusively tied to chargebacks and regulatory fines for the institution—never the holistic financial survival of the end user. As long as the transaction clears KYC and AML checklists, the system treats it as valid. The bank gets its interchange or wire fee. The platform gets its liquidity. The victim gets a caseworker and a press release.
Dismantling the Regulatory Theater
Governments love to respond to these crises with compliance theater. They mandate extra checkboxes, pop-up warnings that say "Are you sure you want to send money to a stranger?", and endless disclaimers that no human ever reads.
This is security by liability waiver. It exists so that banks can point to a terms-of-service agreement and say, "Well, she clicked accept."
Real security requires reversing the burden of velocity. In high-value asset transfers, speed is the enemy of safety. If a transaction involves a sum that exceeds a certain percentage of a user's historical account balance, or if it deviates from established behavioral baselines, the system should deliberately break. It should demand out-of-band verification that cannot be faked by a deepfake video call or a spoofed phone number.
Instead, banks spend millions on machine learning models designed to maximize ad targeting and cross-selling, while fraud detection is relegated to legacy rules engines that catch obvious Nigerian scams while letting institutional-scale synthetic fraud waltz right through the front door.
The Brutal Truth About Financial Literacy
Stop telling people to get educated. Stop running public service announcements telling grandmothers not to trust strangers on WhatsApp.
It is insulting, and it is empirically ineffective. You cannot educate your way out of a cognitive architecture that has been hacked by professional psychological syndicates backed by millions in illicit capital. You cannot read your way past an interface specifically designed to bypass your prefrontal cortex using dopamine loops and manufactured urgency.
If you own wealth, you are a target. If you think your skepticism protects you, you are already halfway to becoming a statistic.
The next time you read about an octogenarian losing millions, do not shake your head at her gullibility. Look at the rails that carried her money across international borders in three seconds flat, completely unquestioned by the algorithms sworn to protect her.
Until we force financial institutions to take responsibility for the integrity of their destination endpoints rather than just washing their hands at the wire transfer gateway, the losses will keep mounting.
And no amount of digital literacy workshops is going to save us from the machine we built.