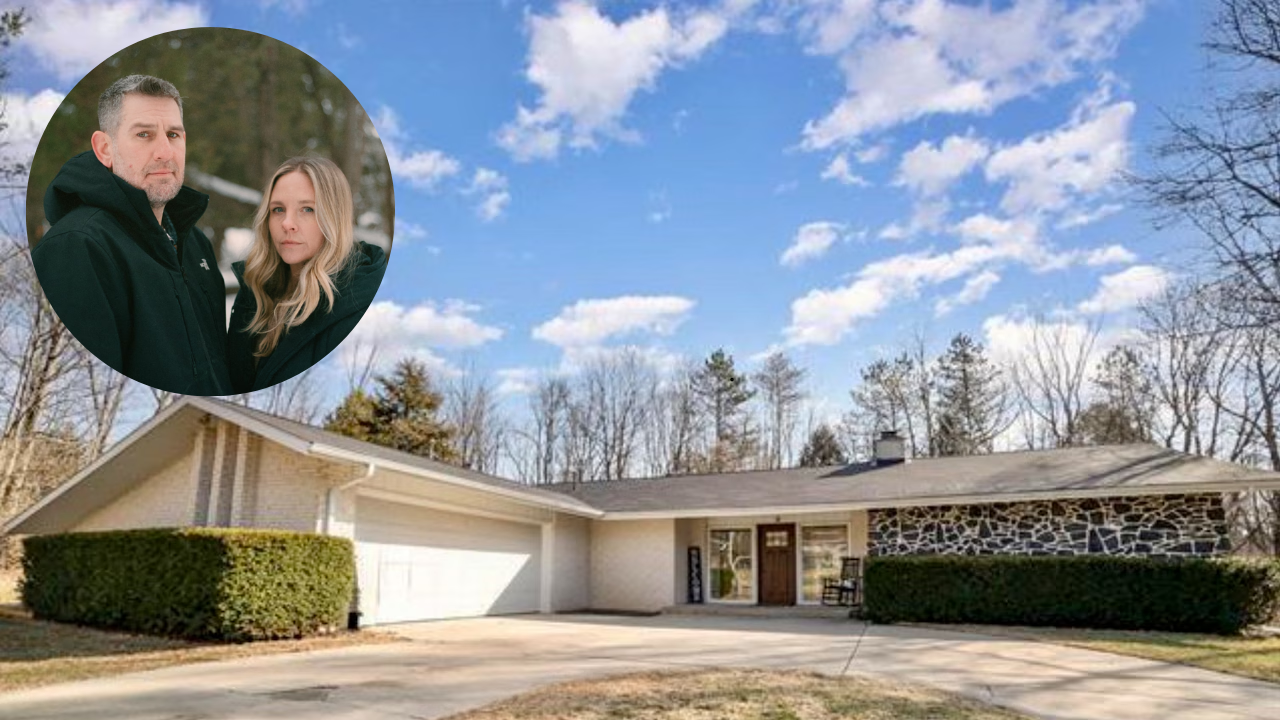
When a municipal government seizes a residential asset valued at $194,400 to satisfy a $2,242 tax delinquency and subsequently liquidates it for $76,008 while retaining the entirety of the proceeds, the transaction exposes a foundational vulnerability in property tax enforcement mechanisms. This is not merely an anecdote of administrative overreach; it represents a systemic market failure where statutory collection frameworks operate with asymmetric incentives, stripping constitutional property rights under the color of law.
To deconstruct this phenomenon, one must analyze the mechanics of tax lien foreclosure, the pricing inefficiencies of municipal auctions, and the legal doctrines governing surplus equity retention.
The Economic Mechanics of Tax Delinquency and Seizure
Property taxation functions as a senior lien on real estate. When a property owner fails to remit payment, the taxing authority acquires a legal claim against the asset. The nominal liability in the referenced case—$2,242—represents a negligible fraction of the underlying asset value, creating an extreme liquidity mismatch.
[Property Value: $194,400] >>> [Tax Liability: $2,242] >>> [Asymmetric Seizure Trigger]
In a functioning market, a liquidity shortfall of this magnitude is resolved through credit markets, short-term debt financing, or partial asset liquidation. However, municipal statutory frameworks often bypass these market-clearing mechanisms by imposing rigid deadlines coupled with punitive penalty structures.
The economic inefficiency compounds at the point of seizure. Tax foreclosure laws in various jurisdictions permit counties to acquire title to delinquent properties without compensating the owner for the equity exceeding the tax debt. This creates a perverse fiscal incentive. Municipalities or their private collection partners are effectively empowered to capture asymmetric economic rents.
The cost function for the municipality is fixed:
$$\text{Cost} = \text{Administrative Fees} + \text{Outstanding Tax Principal} + \text{Accumulated Penalties}$$
In contrast, the potential upside is unbounded, limited only by the fair market value of the seized real estate. When a jurisdiction sells the asset for $76,008 and absorbs the surplus rather than remitting the excess capital to the debtor, the system transitions from a tax collection mechanism to a state-sanctioned wealth transfer protocol.
Valuation Discrepancies in Distressed Municipal Auctions
The disparity between the estimated property value of $194,400 and the municipal auction liquidation price of $76,008 illustrates the structural pricing inefficiencies inherent in forced government sales.
Public tax auctions operate under severe market constraints that depress asset valuations:
- Information Asymmetry: Prospective buyers frequently face restrictions on conducting interior physical inspections, leading to an aggressive risk discount to account for deferred maintenance or latent structural defects.
- Title Encumbrance and Redemption Risks: Depending on statutory rules, properties sold at tax sales may carry clouded titles or remain subject to post-sale redemption windows, deterring institutional capital and limiting the buyer pool to speculative local investors.
- Forced Liquidation Velocity: Municipalities prioritize administrative closure velocity over price optimization, scheduling sales with minimal marketing lead times.
This forced-sale discount ensures that the asset trades well below its fundamental economic value. When combined with the legal framework allowing the state to keep the surplus, the debtor suffers a dual loss: the inherent equity discount of the auction format, followed by the complete confiscation of whatever proceeds are realized.
Legal Precedents and the Doctrine of Surplus Equity
Historically, statutory schemes governing property tax foreclosures treated the proceeding strictly as an in rem action against the property rather than an action against the debtor. Under this legal fiction, failure to pay taxes extinguished all property interests, and the government assumed absolute title.
However, economic analysis and constitutional jurisprudence increasingly recognize that equity in real property constitutes a protected property interest under the Takings Clause of the Fifth Amendment. When a government entity seizes property worth significantly more than the total debt owed, retaining the surplus constitutes an uncompensated taking of private property for public use.
The financial calculus of this legal structure distorts municipal budgeting behavior. In jurisdictions where delinquent tax collection is outsourced or where surplus retention flows directly into general operational funds, local agencies face a negative incentive to facilitate workout agreements or payment plans with distressed homeowners. A $2,242 debt managed through standard collection practices yields only the tax revenue plus standard interest. The same debt processed through aggressive foreclosure and underpriced liquidation can yield tens of thousands of dollars in windfalls for institutional actors or municipal coffers, depending on statutory distribution rules.
Systemic Vulnerabilities in the Enforcement Chain
Evaluating why such outcomes persist requires mapping the breakdown points across the enforcement lifecycle.
Delinquency Identified ---> Notice Thresholds Met ---> Summary Judgment ---> Forced Auction ---> Surplus Confiscation
Each node in this sequence features a structural vulnerability:
- Notification Friction: Vulnerable populations—often elderly, financially illiterate, or experiencing acute economic distress—frequently fail to navigate complex statutory notice requirements, converting a curable administrative notice into a terminal default.
- Absence of Mandatory Equity Protection: Unlike mortgage foreclosures, where judicial oversight and mandatory surplus distribution to the mortgagor are standard protections, tax foreclosures in outlier jurisdictions lack a statutory mechanism to monetize the property at fair market value and return the residual balance to the owner.
- Asymmetric Legal Representation: Delinquent homeowners rarely retain legal counsel during the early administrative phases of tax delinquency due to capital constraints, allowing municipalities to execute foreclosures uncontested.
Capital Allocation and Risk Mitigation Strategies
For institutional market participants, distressed municipal tax systems represent a distinct asset class characterized by high legal risk and high potential yield. Investors target tax liens or tax deeds specifically to exploit the spread between the acquisition cost (the tax debt) and the intrinsic real estate value.
For policymakers and municipal strategists seeking to optimize tax recovery without violating basic economic equity principles, structural reforms require aligning collection mechanisms with market realities:
- Mandatory Surplus Liquidation Protocols: Requiring municipalities to sell seized properties via open-market brokerages rather than restricted auctions to maximize recovery value.
- Residual Remittance Mandates: Legally obligating the taxing authority to deduct all back taxes, penalties, and administrative expenses, then placing the remaining balance into an escrow account for the dispossessed homeowner.
- Structured Workout Integration: Mandating a statutory mediation or structured repayment window before title transfer can be initiated for primary residences where the equity-to-debt ratio exceeds a defined threshold.
The structural failure documented in cases of extreme equity confiscation highlights the necessity of separating the state's revenue collection function from asset expropriation. Until municipal frameworks integrate mandatory equity protection, the tax foreclosure process will continue to function as an engine of wealth destruction for vulnerable property owners.