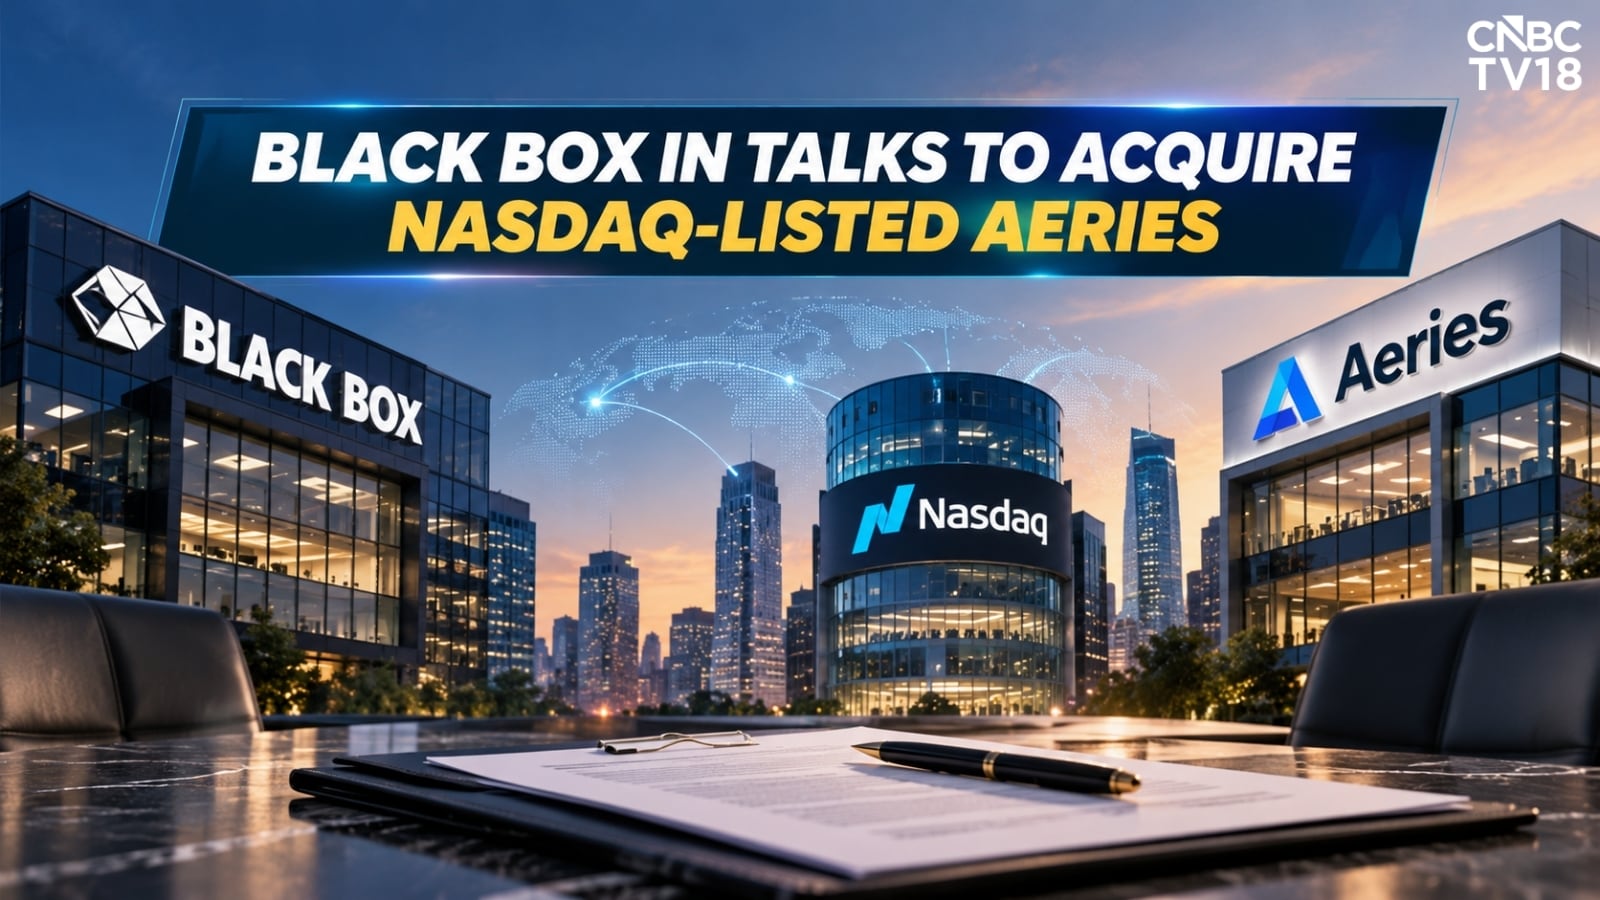
Digital infrastructure provider Black Box is currently engaged in early-stage discussions to acquire Nasdaq-listed Aeries Technology for an estimated valuation between $70 million and $90 million. This potential M&A move, bubbling up against a backdrop of tight margins and rising operational overhead across the enterprise tech sector, highlights the brutal math facing smaller, publicly traded service firms. Aeries, carrying a market capitalization hovering around $36 million, finds itself caught in the classic trap of the micro-cap public company: solid operational revenue offset by the crushing administrative costs of maintaining a Nasdaq listing and thin trading liquidity.
To understand why Black Box—backed by the Essar Group and freshly buoyed by a massive $131 million data center contract from a U.S. hyperscaler—is sniffing around an acquisition, one must examine the actual financial contours of both organizations. Aeries posted $70 million in revenue for fiscal year 2026 alongside an Adjusted EBITDA of $8.3 million, rebounding significantly from prior bottom-line contractions. Yet, public markets have routinely failed to price these operational recoveries into the stock. When a company trades below or near its fundamental asset value while bearing the compliance burden of a U.S. stock exchange listing, it becomes an inevitable target for larger, cash-generative strategic buyers.
Black Box operates in an entirely different weight class. With consolidated revenues reaching ₹6,322 crore and an EBITDA of ₹570 crore underpinned by a $792 million order backlog, the company possesses the balance sheet scale necessary to absorb smaller service providers without straining its liquidity. Buying out Aeries at a proposed valuation range of $70 million to $90 million would represent a substantial premium over Aeries' standalone market cap, offering public shareholders an exit route they might otherwise wait years to realize through organic market appreciation.
The strategic rationale extends far beyond simple balance sheet arithmetic. Modern IT service integrators are scrambling to secure specialized delivery talent, proprietary workflow structures, and deep client relationships to service surging enterprise demands in artificial intelligence infrastructure and cloud architecture. Aeries brings specialized professional services and consulting infrastructure that can slot directly into Black Box's expanding global footprint. This follows a broader pattern of corporate maneuvers, such as Black Box forging strategic alliances to scale AI-led operations. Consolidating an established delivery engine cuts down the multi-year timeline required to build equivalent capabilities from scratch.
However, early-stage talks frequently founder on the rocks of structural execution and valuation disagreements. Cross-border tech acquisitions introduce layers of regulatory complexity, cultural friction, and integration drag that can erode anticipated margins if management misjudges the friction points. For Aeries, remaining independent in a market that heavily penalizes sub-scale technology firms offers diminishing returns, yet accepting an acquisition requires navigating intricate deal terms regarding funding and timeline finalization. As these exploratory negotiations continue to develop, the outcome will serve as a bellwether for how mid-tier technology providers choose to survive an increasingly unforgiving corporate landscape