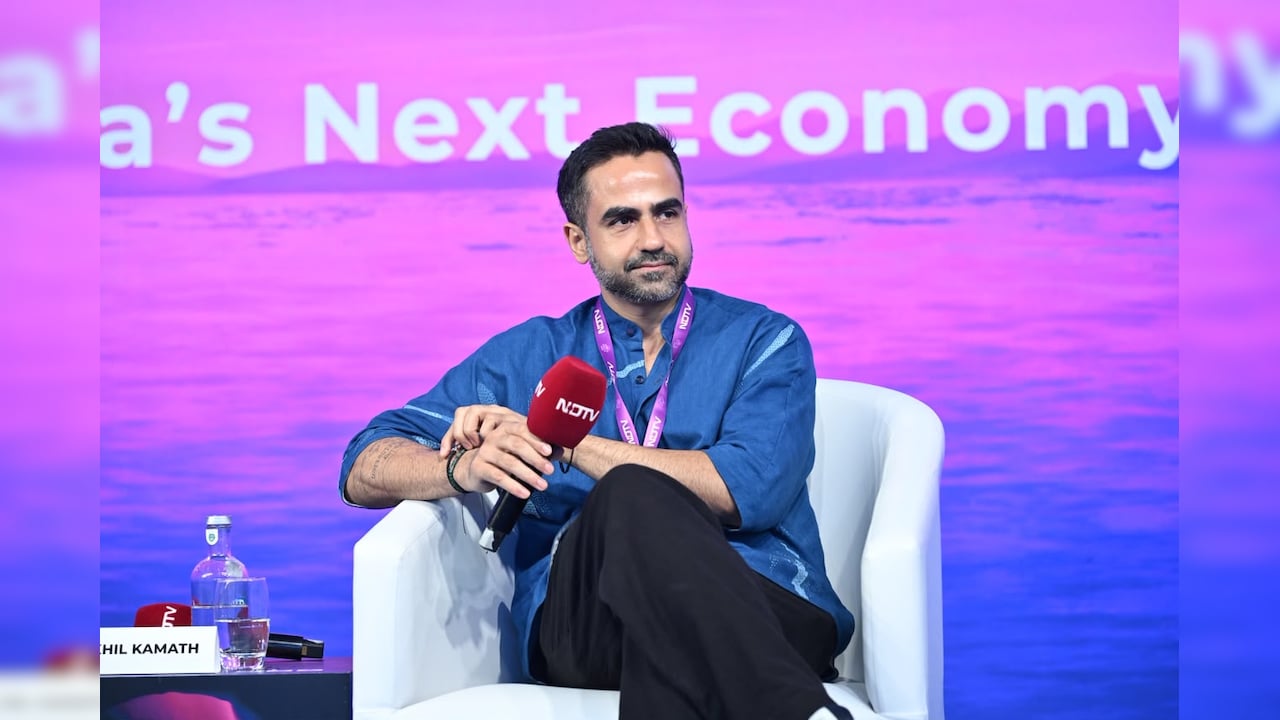
When Zerodha co-founder Nikhil Kamath remarked at the NDTV World Summit that "Groww did well" and that India needs hundreds of Growws and Zerodhas to build a market commensurate with a developed economy, headlines framed the moment as generous sportsmanship from a market incumbent. That framing misses the structural economics underneath. A soundbite praising a rival over active client counts treats user acquisition and capital market depth as interchangeable variables. They are not. Active retail account growth measures distribution reach and transaction frequency, whereas deep, resilient equity markets depend on sustained household asset allocation, net capital formation, and market microstructure that does not systematically penalize non-institutional participants.
Standard coverage of the Zerodha–Groww dynamic rarely separates three distinct layers of the business: top-of-funnel onboarding velocity, unit revenue per active trader, and long-term balance-sheet stickiness. Confusing active client market share with durable economic dominance leads operators and observers to misread competitive threats. A platform can lead in active client counts while facing sharper unit-economics sensitivity to regulatory fee changes, derivatives volume swings, and customer acquisition costs, while an incumbent with slower top-of-funnel growth may hold higher-retention accounts or broader wealth adjacencies.
Deconstructing the Competitor Narrative
News coverage of Kamath's remarks centers on a straightforward chain of reasoning: equity investor penetration in India sits in the single digits (described by Kamath as sub-5 percent), Groww has captured major traction in active clients, and therefore competition among brokers expands the pie rather than merely redistributing fixed share. Alongside that growth argument, Kamath paired his defense of speculators and price discovery with calls for a fairer playing field for retail participants relative to high-frequency traders and transaction-based tax friction.
Viewed analytically, the surface story contains two real observations—low broad equity penetration and intense competitive expansion across retail broking—alongside an analytical shortcut. Saying a market needs "hundreds" of scaled brokers treats customer acquisition as the primary constraint on market development. In practice, onboarding friction has already fallen sharply through digital KYC and mobile-first interfaces. The harder bottlenecks are financial literacy, household savings allocation outside physical and fixed-income assets, net realized returns for retail traders, and regulatory rules governing derivatives and market access.
Known Facts Versus Educated Hypotheses
Separating verified market realities from strategic interpretation keeps the diagnosis grounded:
- Known fact: Nikhil Kamath publicly praised Groww's performance during his NDTV World Summit appearance in October 2026, calling for broader market participation across investors, traders, and speculators as well as more intermediaries.
- Known fact: Public debate around Zerodha and Groww in 2026 has also highlighted distinct product and monetization choices—such as controversies over direct versus regular mutual fund plans and advisory/subscription tiers—alongside broader scrutiny of retail speculation and transaction costs.
- Educated hypothesis: Praising a fast-growing challenger while advocating for retail-friendly tax and market-microstructure rules allows an established incumbent to frame itself as an ecosystem builder rather than a defensive incumbent losing active-client share.
- Educated hypothesis: Rapid client acquisition by mass-market apps often brings a higher proportion of small-ticket or cyclical traders whose activity contracts faster during market drawdowns or regulatory tightening than high-tenure multi-asset accounts.
The Three Pillars of Retail Broking Advantage
To evaluate any rivalry between discount and mass-market brokers without getting distracted by headline client milestones, assess performance across three pillars: Distribution Velocity, Revenue Mix Resilience, and Execution and Microstructure.
Distribution Velocity
Distribution velocity governs how cheaply and quickly a platform converts uninvested or casual users into funded accounts. Mass-market consumer apps excel here when onboarding flows are frictionless, product entry points feel approachable to first-time participants, and organic word-of-mouth compounds across younger cohorts. High velocity expands total addressable reach, particularly among first-time equity and mutual fund buyers.
The operational catch is that velocity alone does not guarantee durable lifetime value. First-time retail users frequently test the market with small capital allocations or short-horizon trades. If early outcomes are poor or market volatility spikes, churn or dormancy rises quickly, forcing continuous top-of-funnel spend just to replace inactive accounts.
Revenue Mix Resilience
Revenue mix resilience measures how exposed a broker's earnings are to a single fee pool or cyclical trading behavior. Historically, Indian discount brokers built extraordinary operating leverage on low-cost equity delivery paired with high-volume equity and index derivatives activity, while offering zero-commission direct mutual funds as an acquisition and retention anchor.
When regulatory changes tighten leverage, margins, or contract structures—or when retail derivatives participation cools—monoline or transaction-heavy models feel pressure immediately. Diversifying into wealth management, recurring subscription or advisory layers, or broader asset products can cushion cyclicality, though every monetization shift carries a trade-off between revenue per user and user trust on pricing transparency.
Execution and Microstructure
Execution and microstructure determine whether a platform's users can compete fairly and survive over multi-year cycles. Kamath's point about speculators, high-frequency trading (HFT), and transaction-based taxation touches directly on market microstructure. Speculative liquidity providers help narrow bid-ask spreads and absorb order flow during normal conditions, improving price discovery.
Yet retail traders operating on slower infrastructure and smaller capital pools face structural disadvantages against latency-advantaged algorithmic desks, while cumulative transaction taxes and charges compound rapidly on high-turnover strategies. Even if a broker has zero platform downtime, adverse net expectancy for frequent retail traders erodes the client base over time.
Cause-and-Effect Chains Standard Coverage Misses
A rigorous strategic read traces second- and third-order effects rather than stopping at "more users equals bigger market."
First, more retail participants do not automatically equal net wealth creation. If new entrants cluster in short-term speculation rather than long-term compounding, gross order flow rises while net retail capital retained in the market may lag. High turnover generates activity metrics in the short run but can shorten user lifespan if realized losses accumulate after fees and taxes.
Second, regulatory and tax friction alters product economics unevenly. Transaction-based taxes act as a drag proportional to trade count rather than net profit. High-frequency market makers can sometimes offset friction through tight spreads and high turn on institutional setups, whereas directional retail traders face a steeper hurdle rate on every round trip. A broker whose revenue depends heavily on active trading faces an inherent tension: its short-term fee pool grows with activity, yet excessive turnover harms client retention.
Third, product unbundling changes competitive boundaries. When a discount broker champions pure low-cost execution and free direct mutual funds while a rival experiments with assisted or subscription-backed tiers, the battle shifts from pure brokerage price wars to value-versus-cost positioning. Customers who want guidance may pay for convenience, while cost-sensitive DIY investors scrutinize any perceived shift away from pure low-cost execution.
Tactical Playbook for Evaluating and Competing in Retail Broking
Whether you are an operator benchmarking a rival, an analyst covering capital markets platforms, or a product leader designing retention loops, apply a disciplined sequence rather than chasing vanity active-user totals:
- Segment active clients by capital tenure and product breadth. Separate single-product, low-balance accounts from multi-product users holding long-term equity holdings, systematic mutual fund plans, and diversified balances. Active count without funding depth overstates durability.
- Stress-test revenue against volume contractions. Model earnings under lower derivatives turnover and tighter regulatory parameters to see how much profit survives on core cash equities, interest income on client float, and recurring fee lines.
- Audit friction points across the full trade lifecycle. Measure not just sign-up conversion, but net post-cost user outcomes, order-routing reliability during peak volatility, and clarity of fee disclosures.
- Align incentives between platform monetization and user survival. Design nudges, risk warnings, and portfolio tools that extend multi-year participation rather than maximizing short-term churned trades.
Limitations and Strategic Trade-Offs
No operating model escapes trade-offs. Focusing strictly on high-retention, long-term investors lowers immediate transaction velocity and requires patient product investment before monetization matures. Conversely, optimizing aggressively for mass-market sign-ups and high-frequency activity boosts near-term scale and engagement metrics while increasing vulnerability to regulatory shifts, market drawdowns, and reputational pushback when retail traders lose money. Publicly praising rivals in a growing market is smart positioning, but sustainable advantage belongs to the firm whose unit economics hold up after the hype cycle cools.
The sharpest strategic move in Indian retail broking is to compete on funded retention and post-cost investor durability rather than headline active-client milestones. Platforms that pair frictionless onboarding with transparent pricing, strong risk guardrails, and genuine long-term wealth utility will capture the compounding share of India's household savings transition long after short-term trading spikes normalize.