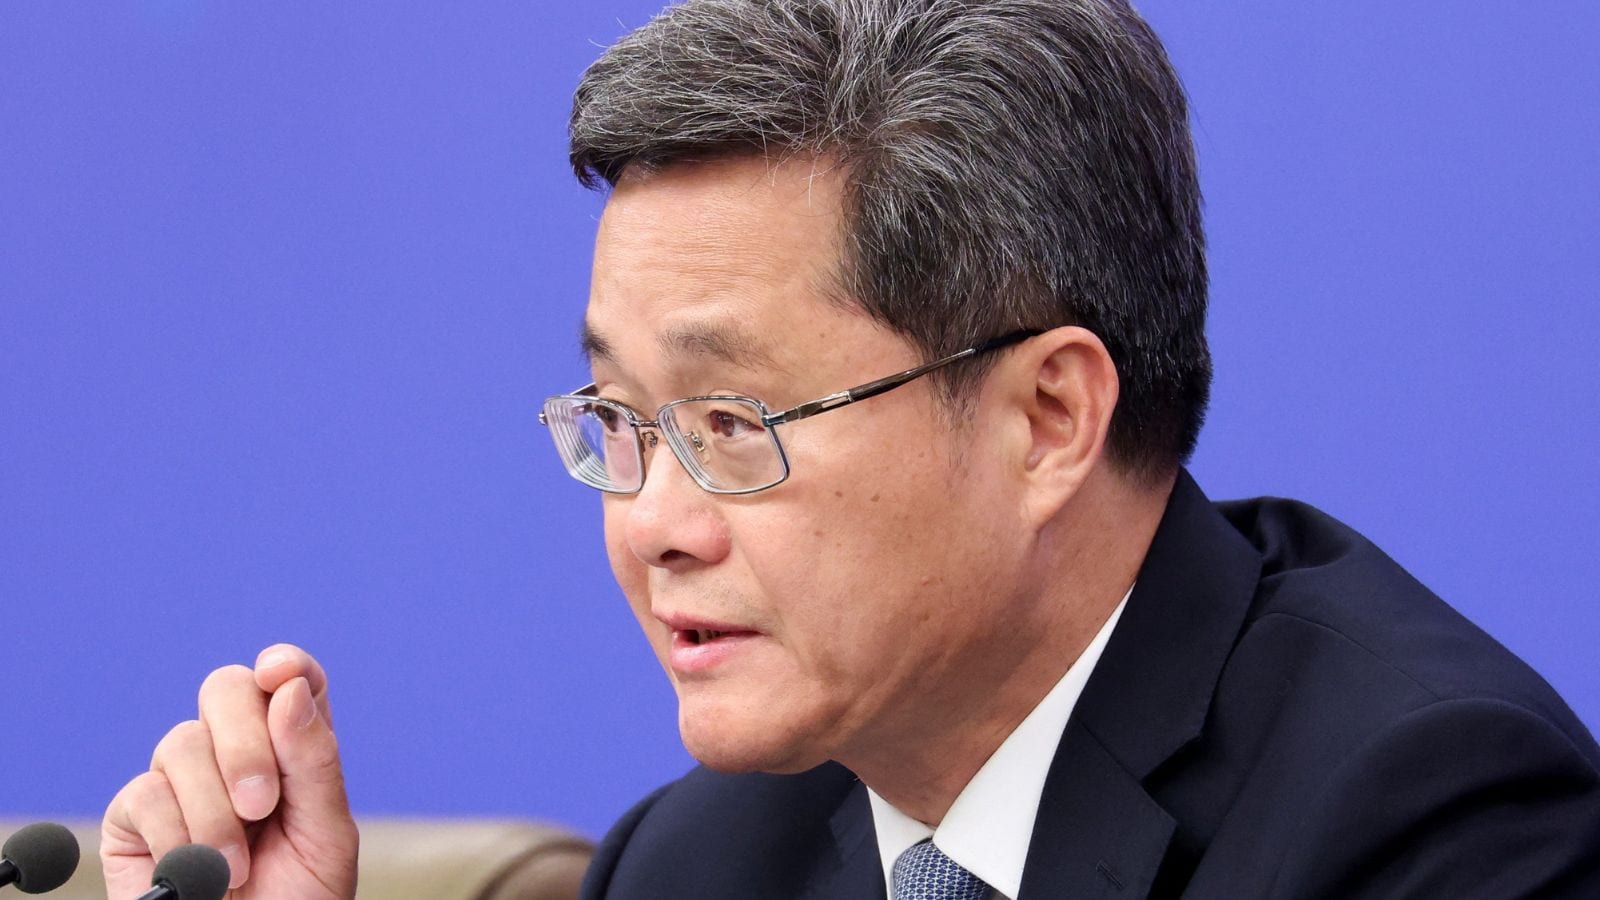
Finance ministers across the Asia-Pacific Economic Cooperation forum have pledged to strengthen policy coordination as trade friction, uneven interest rate paths, and shifting supply chains strain regional economies, according to remarks attributed to Chinese Finance Minister Lan Fo'an. On paper, that pledge sounds like steady diplomatic statesmanship. In practice, getting twenty-one economies with conflicting domestic priorities to move in lockstep is one of the hardest exercises in global economic management.
I have watched dozens of multilateral summits produce glossy communiques that evaporate the moment ministers board their return flights. When officials talk about policy coordination, the phrase often masks a quiet tug-of-war between export-driven manufacturing models, domestic consumption goals, currency stability, and national security concerns. Agreement on a general principle rarely equals agreement on who absorbs the short-term pain when growth slows or capital moves abruptly. Learn more on a similar topic: this related article.
The headline tells you ministers want tighter alignment. The harder question is what kind of alignment is actually achievable in a fractured global economy where fiscal space is tight, debt burdens have climbed, and industrial policy has returned with a vengeance.
Why Pledges Sound Easy Until Domestic Budgets Collide
Every finance ministry walks into an APEC gathering carrying domestic baggage that no regional communique can erase. A minister representing a net commodity exporter faces a very different set of pressures than a minister overseeing a dense manufacturing hub reliant on imported components or a service-heavy economy sensitive to tourism and external demand. Further journalism by Financial Times explores related views on the subject.
When officials call for stronger policy coordination, they are usually pointing to three broad buckets. First is macroeconomic alignment, meaning how fiscal spending and monetary settings interact across borders so one country's sharp tightening or aggressive stimulus does not trigger disorderly capital swings elsewhere. Second is trade and investment resilience, which focuses on keeping supply chains moving without sudden, disruptive choke points. Third is structural reform, covering areas like digital finance, infrastructure financing, and long-term productivity.
None of those goals is controversial in isolation. Trouble starts at the trade-off stage.
Consider a hypothetical example to see how the friction plays out. Suppose Country A relies heavily on manufactured exports and faces softening external orders. Its policymakers might favor targeted fiscal support and a competitive currency posture to protect factory employment. Meanwhile, Country B is fighting stubborn domestic inflation and trying to keep its currency from sliding too far against major benchmarks, which could raise imported food and energy costs for households. Both capitals can sincerely endorse policy coordination at a ministerial table and still pull in opposite directions the following week because their domestic political survival depends on different variables.
That tension is not a sign of bad faith. It is structural. Finance ministers answer to national parliaments, voters, and bond markets first, and to multilateral forums second.
The Gap Between Communique Language and Policy Execution
Multilateral diplomacy has its own vocabulary, and seasoned observers learn to read the verbs carefully. Words like "boost," "enhance," or "strengthen" signal intent rather than binding obligation. Unlike currency unions or formal monetary blocs, APEC operates on consensus and voluntary cooperation rather than enforceable rules or pooled fiscal transfers.
Without enforcement mechanisms, policy coordination relies heavily on information sharing, peer review, and shared analytical frameworks. That has real value. When central banks and finance ministries compare notes early on bank liquidity, cross-border debt rollovers, or shadow-banking exposures, they reduce the chance of flying blind during a sudden shock.
Still, sharing diagnostics is not the same as synchronizing action. Two countries can look at the exact same set of global risk indicators and reach opposite conclusions about whether to loosen credit, expand public investment, or tighten rules on cross-border capital flows.
Currency Pressures and the Shadow of Geopolitics
Money never moves in a vacuum across the Pacific. Exchange rates sit right at the intersection of trade competitiveness, inflation control, external debt servicing, and political prestige.
When major global interest rates diverge, smaller or mid-sized economies often feel the squeeze first. Capital tends to chase yield or perceived safety, putting downward pressure on local currencies and forcing domestic policymakers into an awkward corner. Raise rates to defend the currency and risk choking off local business investment. Let the currency drift lower and risk imported inflation plus higher local-currency costs for dollar-denominated debt.
Regional policy coordination is frequently invoked as a stabilizer in moments like these. Yet major economies also have strategic interests that complicate purely technocratic fixes. Export controls, tariff disputes, technology restrictions, and competing infrastructure initiatives shape how governments view cross-border economic interdependence.
A finance minister cannot separate balance-sheet arithmetic from geopolitical reality. If a supply chain is viewed through a national security lens rather than a pure cost-efficiency lens, purely financial coordination will hit ceiling after ceiling.
Supply Chains Are Rewiring Without a Single Master Plan
For years, regional integration in the Asia-Pacific was driven by layered production networks. Raw materials and components crossed borders multiple times before final assembly, creating dense webs of mutual reliance.
Now those networks are being diversified, duplicated, or shortened. Firms are adding secondary suppliers, shifting certain assembly stages to neighboring countries, and holding larger buffers against logistics disruptions. That shift changes the job of finance ministries. Instead of simply facilitating frictionless trade flows, officials have to think about trade finance resilience, customs digitization, port and logistics bottlenecks, and how industrial subsidies in one market affect competitors next door.
If every government responds to supply chain anxiety with unilateral subsidies or protective barriers, the region risks higher costs and lower overall efficiency. Coordinated policy is meant to keep channels open and predictable, even as business models adapt to a noisier world.
Fiscal Space Is Tighter Than the Rhetoric Suggests
Walk past the polite diplomatic framing at any economic summit and look at the balance sheets. Many economies across the region are dealing with heavier public debt loads than they carried prior to the pandemic era, alongside aging populations, healthcare commitments, and climate adaptation needs.
Spending your way out of every slowdown is harder than it used to be. Bond vigilantes and credit rating agencies pay close attention to fiscal deficits and debt trajectories, especially when borrowing costs stay elevated compared with the ultra-low-rate years of the 2010s.
That reality sharpens the stakes of policy coordination. When fiscal room is limited, wasteful or poorly timed stimulus carries a higher price tag. Coordinated attention to debt sustainability, public investment quality, and domestic demand becomes essential so growth does not rest solely on external exports or credit bubbles.
Domestic Consumption Remains the Unfinished Business
Many economies in the Asia-Pacific built remarkable prosperity on export-led growth. That model delivered rapid industrialization, rising incomes, and deep integration into global markets.
The catch is obvious whenever global trade slows or faces political headwinds. Over-reliance on external demand leaves an economy exposed to shifts far beyond its borders. Strengthening domestic household consumption—through social safety nets, healthcare access, wage growth, and fairer tax structures—is often cited as a durable buffer, yet shifting deeply ingrained growth models takes years, not quarters.
Finance ministers know this. Changing an economy's growth engine is politically delicate because entrenched sectors benefit from the status quo while broad-based household gains materialize more slowly.
What Actually Moves the Needle After the Summit Ends
Skepticism about ministerial pledges is healthy, provided it does not slip into lazy cynicism. International forums do not solve every crisis, nor do they erase conflicting national interests. They do, however, create regular channels where officials can test assumptions, calm market jitters, and prevent small misunderstandings from spiraling into wider financial or trade standoffs.
To judge whether talk of policy coordination amounts to real progress rather than routine diplomatic theater, watch concrete follow-through rather than summit speeches. Look at whether cross-border payment and settlement frictions are actually reduced for businesses and travelers. Watch how governments handle trade and investment rules when domestic industries lobby for protection. Pay attention to how multilateral development banks and regional financing arrangements coordinate on infrastructure and crisis liquidity when a shock hits.
In a world split by competing strategic priorities and uneven recovery paths, perfect harmony among finance ministers is a fantasy. Practical, targeted alignment on shared choke points is harder, slower, and far more consequential.



