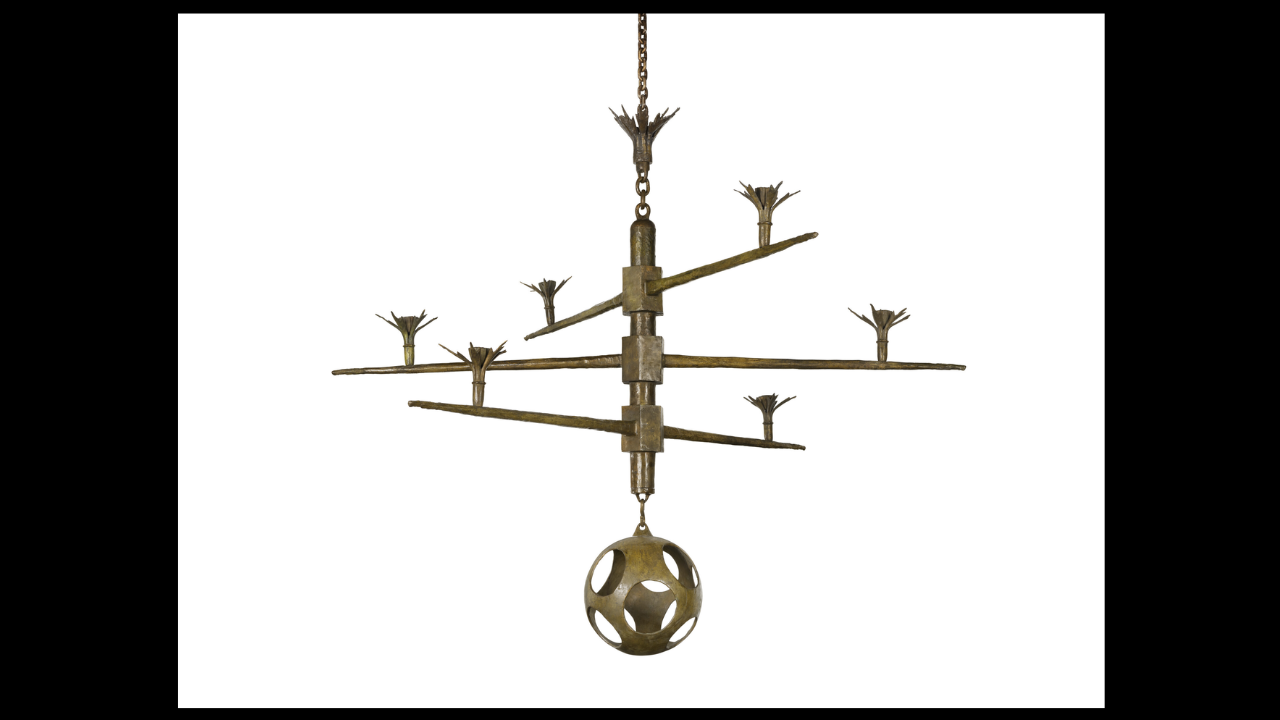
Every few months, the art world serves up a comforting fairy tale. An ordinary artist walks into a dusty antique shop on Marylebone High Street in the 1960s, spots a tarnished bronze fixture hanging from the ceiling, drops £250, and hangs it in his studio for fifty years. Decades later, Christie’s brings down the hammer at £2.922 million.
Cue the breathless headlines. Cue the weekend treasure hunters descending on Portobello Road with magnifying glasses and delusions of retirement. Meanwhile, you can read similar developments here: Why SoftBank's Reported $50 Billion Malaysia Bet Could Backfire on Both Sides.
Here is the cold water nobody in the auction house press room will throw on this story. That £2.922 million windfall is not an investment strategy. It is not proof that "good taste pays off." And it certainly is not a repeatable blueprint for building wealth in the secondary art market.
If you treat the John Craxton Giacometti chandelier sale as anything other than a statistical anomaly, you are going to lose your shirt. To explore the full picture, check out the detailed article by Bloomberg.
The Lazy Consensus of the "Hidden Masterpiece"
Mainstream coverage of the Craxton chandelier—originally designed by Alberto Giacometti around 1947 for Peter Watson, co-founder of Horizon magazine—peddles a seductive lie. The narrative goes like this: buy what you love, trust your eye, hold onto it long enough, and the market will eventually reward your discernment.
That narrative sells newspapers and drives foot traffic to regional auction houses. It is also financial poison.
When journalists frame this sale as a triumph of aesthetic intuition, they deliberately omit the mathematical graveyard of the decorative arts market. For every Craxton who accidentally buys an undocumented Alberto Giacometti bronze lighting fixture for the price of a used car, ten thousand buyers spend £250 on mid-century knockoffs, Victorian reproductions, and corroded brass junk that will never clear a £50 reserve at a local estate sale.
I have watched private clients burn through seven-figure budgets chasing "sleeper" lots at provincial auctions because they read stories like this. They convince themselves they possess a magic eye. They mistake survivorship bias for alpha.
Let’s look at the actual mechanics of the Craxton sale. John Craxton wasn't a random bloke wandering off the street. He was a celebrated British Neo-Romantic painter deeply embedded in London’s post-war intellectual and artistic circles. He knew Peter Watson. He moved in the exact milieu where Giacometti’s functional commissions circulated. Even then, Craxton didn't buy it as a calculated financial play; he bought it because he needed a light fixture and liked the shape. The £2.922 million result at Christie’s in 2023 wasn't the payoff of a savvy collector's thesis. It was pure, unrepeatable historical accident.
Why "Buy What You Love" Is Terrible Financial Advice
Art advisors love telling novices to "buy what you love." It sounds noble. It removes the pressure of financial performance. It also absolves the advisor when the work loses 70% of its value the second it walks out the gallery door.
If you are buying a £500 print to hang over your sofa because the colors match your rug, buy what you love. Stop reading right now and enjoy your wall decor.
If you are deploying capital with any expectation of preservation or appreciation, "buy what you love" is malpractice.
The fine art and collectible design markets do not reward affection. They reward provenance, catalogue raisonné inclusion, and institutional consensus.
The Real Value Drivers Nobody Mentions
When Christie’s valued that chandelier at £1.5 million to £2.5 million before pushing it to £2.922 million with fees, the price had almost nothing to do with the bronze itself. Strip away the paperwork, and you have a fragile, oxidized metal frame with glass cups. You could hire a master foundry in Pietrasanta to cast an identical replica tomorrow for £15,000.
What the winning bidder actually bought was an airtight chain of custody verified by the Comité Giacometti:
- The Commission: Direct documentation linking the piece to Peter Watson’s London flat at 120 Pall Mall.
- The Era: Late 1940s, the exact inflection point when Alberto Giacometti pivoted toward the elongated, skeletal forms that define his peak market value.
- The Scarcity: Unlike Giacometti’s editions of L'Homme qui marche or his standard-issue bronze lamps produced for Jean-Michel Frank, bespoke ceiling fixtures from this specific period barely exist outside private foundations.
Without the Comité Giacometti’s stamp of authenticity, that £2.922 million chandelier is worth scrap metal prices. You cannot sell an unauthenticated Giacometti at a major auction house. You cannot insure it at replacement value. You cannot borrow against it.
The Brutal Truth About Authentication Cartels
Here is the part of the art market that terrifies outsiders once they actually step inside the velvet rope.
In almost every major modernist estate—Giacometti, Warhol, Basquiat, Calder—value is controlled by a tiny, unaccountable committee or foundation. Their word is absolute law. If the Comité Giacometti decides a bronze has the wrong patina, a slightly off-kilter weld, or a gap in its pre-1966 history, the piece is dead. Permanently. Even if the artist actually made it with their own hands.
I have sat across the table from devastated heirs holding genuine family heirlooms that were effectively wiped off the financial map because an authentication board declined to issue a certificate. There is no appeal process. There is no regulatory oversight. And if you push too hard, some foundations reserve the right to retain or destroy works they deem counterfeit, depending on the jurisdiction.
When you hunt for "sleepers" in flea markets and antique shops, you aren't just betting against the odds of finding a lost masterpiece. You are betting that fifty years later, a Parisian committee will agree with your hunch.
The Hidden Costs of the "Long Hold"
Let’s do the math that lifestyle journalists always skip.
In 1960s London, £250 was roughly equivalent to £5,000–£6,000 in modern purchasing power. Turning £6,000 into £2.922 million over nearly sixty years represents an annualized return of roughly 11%.
On paper, an 11% compound annual growth rate looks phenomenal. In reality, holding physical art and collectible design carries massive, silent drag:
- Illiquidity: You cannot sell a major Giacometti on a Tuesday afternoon when you need cash. You wait six months for an evening sale slot in London or New York.
- Transaction Friction: Auction houses extract brutal vigorish. Between seller’s commissions, marketing fees, photography charges, insurance, and the buyer’s premium (which sits around 20% to 26% at major houses), roughly a quarter to a third of the transaction value evaporates into the auction house’s balance sheet.
- Fragility and Storage: Fine art doesn't sit quietly in a brokerage account. It requires climate control, specialized fine-art transit, and bespoke insurance policies that eat 0.5% to 1.5% of the appraised value every single year.
Had Craxton taken that same £250 in 1965 and dropped it into a boring, zero-effort global equity index with dividends reinvested, he wouldn't have had a cool story for Christie’s press release, nor would he have beaten the 11% outlier return—but he also wouldn't have risked a 99.9% probability of total loss.
People Also Ask (And Why the Questions Are Wrong)
When stories like the Giacometti chandelier go viral, search engines flood with predictable questions from hopeful amateurs. Let’s dismantle them one by one.
"How can I spot valuable antiques at flea markets?"
You can’t, at least not reliably enough to beat the market. The internet killed the information asymmetry that made 20th-century sleeper hunting possible. In 1965, an antique dealer on Marylebone High Street had no database to cross-reference Peter Watson’s apartment furnishings. Today, every dealer in every provincial town has Google Lens, Artnet, and LiveAuctioneers on their phone before they even price an item. If a piece is sitting in a shop for £250 in 2026, it has already been scanned by five dealers and a dozen pickers.
"Are Giacometti lamps and chandeliers still a good investment?"
Buying an authenticated Giacometti decorative object at retail or auction today is wealth preservation, not wealth creation. You are buying at the top of the consensus curve. The exponential growth phase happened between 1980 and 2015, when billionaire collectors reclassified decorative design from "furniture" into "functional sculpture." Buying at £3 million means you need a future buyer willing to pay £5 million after fees just for you to break even.
"What is the next underrated artist or designer to buy right now?"
The moment an artist is named in an article like this, the arbitrage window is already closed. True outperformance in art happens exclusively when you buy deeply unfashionable work before institutional curators rehabilitate the artist's reputation—and you are willing to hold illiquid assets for twenty years with zero guarantee that rehabilitation ever comes.
How Real Insiders Actually Play the Market
If you want to stop playing the lottery and start operating like a serious market participant, abandon the treasure-hunt fantasy entirely.
First, buy liquidity, not stories. In the art and design world, liquidity lives in recognizable editions and well-documented mid-career markets where transparent auction comps exist every six months. An obscure one-off chandelier with a romantic backstory is a nightmare to price and a nightmare to sell unless it happens to be by a top-ten blue-chip name.
Second, never buy unauthenticated work hoping to "fix" the paperwork later. Discounts on works lacking foundation approval look tempting—often 60% to 80% below market value. That discount exists because smart money knows the odds of getting a certificate are near zero. Let someone else gamble on bureaucratic miracles.
Third, treat the auction house as an adversary, not an advisor. Specialists at Christie’s and Sotheby’s are brilliant art historians, and their job is to maximize the hammer price for the consignor and extract maximum fees for their shareholders. They are not your fiduciaries. Never rely on an auction house condition report without hiring an independent conservator, and never believe an estimate is a floor on value.
The Downside of Ruthless Rationality
Admittedly, viewing the art market strictly through spreadsheets, provenance chains, and fee structures strips away the magic. If everyone operated like a cold-blooded hedge fund manager, nobody would ever rescue weird, unattributed objects from dusty antique shops. John Craxton didn't buy that chandelier because he had a thesis on post-war Swiss bronze casting; he bought it because he was an artist who responded to an object in a room.
That romanticism is what makes living with art worthwhile. Just don't confuse living with art with investing in it.
Keep the fairy tales on your walls, keep your capital in transparent markets, and never bet your financial future on finding a Giacometti on your lunch break.