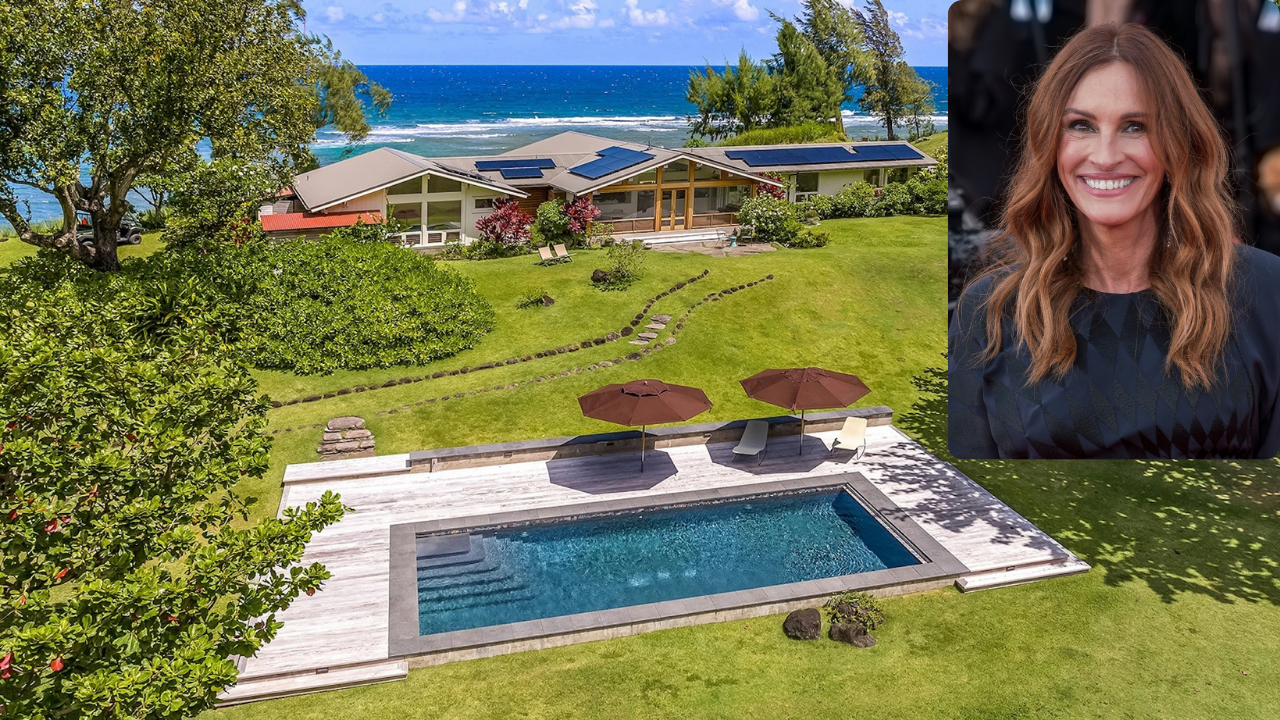
High-end real estate transactions in ultra-prime markets rarely fail due to an absolute lack of capital; they fail due to systemic friction in price discovery and liquidity timing. When Julia Roberts’ 8.3-acre Hawaii estate sold for $20 million after an initial $30 million listing, the transaction became a textbook case study in mispriced optionality and asset stagnation. A thirty percent markdown over the marketing lifecycle does not represent random market volatility. It reveals the structural limits of pricing illiquid, highly idiosyncratic properties in thin geographic markets.
Ultra-prime real estate operates outside the standard housing market equations of comparable sales and square-footage multiples. In lower asset tiers, pricing is a function of historical velocity and standardized demand curves. In the eight-figure asset class, every property is a bespoke financial instrument. The core issue centers on liquidity risk premiums. Sellers of trophy assets frequently mistake replacement cost and emotional attachment for immediate market clearing prices, leading to prolonged days on market.
The Pricing Divergence Function
The initial valuation of $30 million for the Kauai estate established a high-water mark that ignored the fundamental elasticity of the ultra-luxury buyer pool. In macroeconomics, asset pricing relies on the intersection of supply and demand. However, at the top tier of real estate, the demand curve is discontinuous. There is no sloping gradient of buyers; there are discrete, isolated nodes of capital.
Initial List Price ($30M) ---> Prolonged Days on Market ---> Asset Stigmatization ---> Market Clearing Price ($20M)
When an asset enters the market at an inflated price, it triggers three compounding inefficiencies:
- The Stigmatization Effect: High-net-worth buyers monitor trophy assets for years. A property that lingers without activity signals a motivated seller or inherent structural defects, even if the only flaw is initial overpricing.
- Opportunity Cost of Capital: Ultra-prime buyers deploy capital where velocity and appreciation overlap. Tied-up capital in an illiquid asset carries a hidden holding cost, including maintenance, property taxes, and security overhead on extensive acreage.
- The Liquidity Discount: To clear the market after extended exposure, sellers must offer a substantial discount to offset the perceived baggage of the prolonged listing history. The $10 million delta between the opening bid and final settlement reflects this forced liquidity premium.
Asset Idiosyncrasy and Geographic Thinness
The Kauai market differs fundamentally from metropolitan hubs like Manhattan or London. In dense urban centers, a deep pool of corporate executives, foreign investors, and domestic buyers ensures a continuous turnover of multi-million-dollar assets. Kauai represents a thin market characterized by low transaction frequency and specialized lifestyle utility.
An 8.3-acre estate combines high land value with specialized improvements. Large parcels in prime coastal locations are structurally scarce, which creates a psychological trap for sellers. Scarcity does not automatically equal liquidity. If a property requires a specific buyer who values agricultural acreage, ocean frontage, and privacy in equal measure, the addressable market shrinks to a fraction of a percent of global wealth holders.
The cost function of holding such an asset escalates annually. Unlike equities, which generate liquidity through dividends or secondary market sales, a sprawling estate requires capital expenditure just to maintain its baseline condition. When carrying costs outpace expected appreciation, the net present value of the asset declines for any rational buyer, forcing the seller to adjust expectations downward.
Valuation Methodologies for Trophy Real Estate
Traditional appraisal methods rely heavily on historical comparables. In the $20 million to $50 million bracket, comparables are frequently irrelevant because no two trophy properties share identical attributes. View corridors, historical provenance, privacy vectors, and architectural pedigree defy standardized valuation metrics.
Strategic analysts must apply alternative evaluation frameworks:
- Replacement Cost Minus Obsolescence: Calculating the current cost to acquire equivalent land and replicate the physical structures, discounted for functional and economic obsolescence.
- Yield-Adjusted Opportunity Modeling: Evaluating what the $20 million to $30 million in capital could yield in alternative asset classes over the anticipated holding period, offset by the non-financial utility of the estate.
- Liquidity Horizon Analysis: Measuring the time-to-sale velocity of competing properties within the same micro-market to establish a realistic exit window before forced price compression occurs.
Sellers who miscalculate these variables find themselves chasing the market down rather than leading it. The initial $30 million tag acted as a barrier to entry rather than a test of the ceiling. By the time the asset adjusted to $20 million, it had absorbed years of holding costs and market friction.
Capital Allocation Realities in Ultra-Prime Portfolios
For ultra-high-net-worth individuals, real estate is rarely just shelter; it is a component of a diversified wealth preservation strategy. When a property undergoes a thirty percent valuation correction, it highlights the vulnerability of illiquid luxury assets during economic shifts or changing generational preferences.
Younger generations of wealth holders prioritize flexibility, sustainability, and operational efficiency over sprawling, maintenance-heavy compounds. Properties that require armies of staff and constant capital expenditure face shrinking buyer pools. The transaction trajectory of the Kauai estate signals that emotional pricing is encountering resistance from sophisticated buyers who run disciplined capital allocation models, even on lifestyle assets.
Valuation accuracy in the top tier requires anchoring prices to current liquidity realities rather than historical peak exuberance. Assets priced correctly from inception avoid the erosion of value caused by prolonged market exposure. When the market forces a $10 million correction, the financial loss extends far beyond the nominal discount, encompassing years of lost capital velocity and unrecoverable holding expenditures.